Agentic payments: the next evolution of commerce, and a new role for financial institutions
22 / 09 / 2026
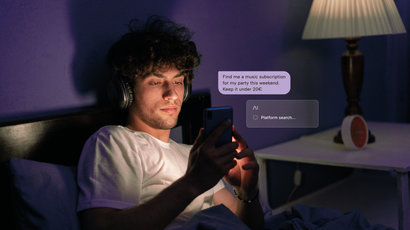
Payments have always evolved with the way consumers shop. From physical point-of-sale payments to e-commerce and mobile commerce, each new channel has changed how a transaction starts and is completed. Agentic commerce is the next step in that evolution: the shift from AI as assistant to AI as actor is what the industry calls agentic commerce. Instead of a consumer navigating a purchase themselves, an AI-agent can search, compare and ultimately make a payment on their behalf.

Projections by Bain and Company and McKinsey forecast that by 2030, agentic commerce could account for nearly 15-25% of US ecommerce transactions and represent $3-5 trillion in consumer spending.
For financial institutions, this is more than a new payment interface. It introduces a new actor into the payment chain and raises a fundamental question: how do you maintain trust and control when an AI-agent is acting on behalf of a customer?
What happens when we shift from human-present to human-not-present?
There are two distinct forms of agentic payments. In a human-present scenario, an AI-agent can handle much of the shopping journey, but the consumer remains involved and confirms the payment. This is a relatively natural evolution of e-commerce.
The bigger shift comes when the human is no longer present during the purchase. A consumer could give an agent an instruction, such as finding a flight within a certain price range, and the agent could search, decide and purchase without asking for confirmation at any step. That changes the requirements for financial institutions. You will need to be able to identify when a transaction is agentic, understand who the agent is acting for and verify whether it has the authority to make the payment to complete the purchase.
Regulation will also need to evolve alongside this technology. Europe's current payment framework is built largely around the customer initiating or authenticating a payment. As agentic commerce develops, the industry will need to establish how existing requirements such as strong customer authentication apply when an authorised agent is acting on the customer's behalf.
Giving AI-agents the right mandate
If consumers delegate purchasing decisions to an AI-agent, they need to be able to define its boundaries. One emerging concept is a digital mandate: a verifiable set of instructions that establishes what an agent is authorised to do. This could include the purpose of a purchase, a payment method or a maximum price.
The mandate effectively links the consumer, the agent and the payment. When the agent reaches a merchant, the ecosystem can verify whether the transaction falls within the customer's authorisation. For banks, this creates a new dimension to authentication and fraud prevention. The question is no longer only “Did the customer authenticate this payment?”, but also “Was this agent authorised to make this payment?”, and “Was the purchase matching the client instruction?”
How do you build a trusted ecosystem?
Agentic payments cannot be developed by a single organisation. Banks, payment networks, payment providers, merchants and AI-platforms all need to work together.
Interoperability is therefore critical. AI-agents need access to accurate, structured and up-to-date information about products, prices and availability. Merchants need to know that an agent is legitimate and authorised to make a purchase. You will need to be able to verify the agent, the customer and the mandate behind the transaction.
This is why common protocols and standards are emerging. Worldline is contributing to this development through initiatives such as Google's Agent Payments Protocol (AP2), or contribution in EMVCo, and by adapting its payment infrastructure to support agent-driven transactions. Worldline and ING, together with Mastercard and VISA have already demonstrated a live end-to-end agentic payment in Europe, showing how agentic transactions can operate using existing payment infrastructure, authentication mechanisms, and our capacity to be agnostic of the scheme behind. The work continues ensuring the sovereign scheme can also provide the required infrastructure for agentic transactions.
Preparing for the shift
- Agentic commerce is still in an early stage, but the direction of travel is clear. Consumers are already using AI-interfaces to search, compare and make purchasing decisions. As payment capabilities become integrated into these interfaces, the shift from e-commerce to agentic commerce will accelerate.
- For financial institutions, preparation starts now. Payment infrastructure needs to be able to recognise and support agentic transactions, emerging protocols need to be monitored and existing capabilities around authentication, fraud prevention and customer protection need to evolve. Most importantly, banks should see agentic commerce not simply as another technology trend, but as an opportunity to reinforce their role as the trust layer of digital commerce.
- As AI agents become more autonomous, customers will need to know that they can delegate payments without giving up control. Financial institutions are uniquely positioned to provide that trust and to help shape how agentic payments develop in the European market.
If you'd like to explore what agentic payments mean for your infrastructure, we will welcome the conversation.
Further resources:
- Agentic Commerce: The next transformation in how people shop, choose and pay
- Worldline, ING and Visa complete a live agentic payment transaction in Europe
- Worldline and ING complete a live end-to-end European agentic payment in production
- Crédit Agricole completes France’s first live agentic transaction
- Video: Agentic e-commerce: a new direction in payments.
FAQ
-
Agentic commerce represents a shift from AI acting as an assistant to AI acting as an autonomous actor. Instead of consumers navigating a purchase themselves, an AI agent can independently search, compare, and execute payments on their behalf based on set instructions.
-
A digital mandate is a verifiable, tamper-proof set of digital instructions that establishes what an AI agent is authorized to do. It links the consumer, the agent, and the payment by defining strict boundaries—such as transaction purpose, approved payment methods, and maximum spending limits—to ensure the agent stays within client authorization.
-
Existing SCA frameworks require direct human initiation or multi-factor authentication at checkout. Under agentic commerce:
- Human-present: SCA occurs naturally as the consumer directly approves the final payment prompt generated by the agent.
- Human-not-present: Authentication shifts upstream. The customer authenticates when setting up the initial digital mandate, allowing the agent to execute subsequent payments autonomously within those verified bounds.